US Stocks open mixed to flat as Monday's AI-led euphoria — which saw AMD cross $1 trillion in market value for the first time, Meta surge 11% on the debut of its Muse AI agent app, and Intel jump 12% — gives way to a more selective tape, with Brent crude bouncing back toward $101 after dipping below $99 on Iran Hormuz reopening reports, a 57.6% probability of an October rate hike weighing on bond-sensitive sectors, and AutoZone's earnings beat alongside Anthropic's November IPO confirmation as the morning's two headline catalysts.
- S&P 500 futures were up just 0.007% to $773.56 on SPY and Nasdaq-100 futures eased 0.085% to $740.84 on QQQ — a notably subdued premarket setup following Monday's blockbuster session in which the Nasdaq Composite set a new record closing high, the Russell 2000 surged 0.79% as the session's standout performer, and the S&P 500 finished narrowly green while the Dow fell 0.36%. Polymarket's "S&P 500 Up or Down on September 22" contract showed just 53% odds of a higher open — essentially coin-flip conviction — reflecting the narrowing breadth Tickmill strategist Patrick Munnelly flagged: "investors still appear willing to take risk, but leadership is narrowing around AI and market breadth matters more with central banks turning hawkish and long-term yields elevated." The 10-year Treasury yield held at 4.97% and the 2-year at 4.77% as of Tuesday's premarket.
- Meta (META) was little changed after its 11.3% Monday surge — the biggest single-session gain for the stock since its February 2023 earnings blowout — after the company's Muse AI agent app reached the No. 1 spot on the App Store. AMD (AMD) crossed $1 trillion in market capitalization for the first time Monday, closing at a record high, while Intel (INTC) jumped more than 12% — its best session since the company announced its Apple chip partnership in June. In Tuesday's premarket, Meta added about 0.5% and Alphabet rose 0.8%, while Nvidia slipped 0.2% and US-listed TSMC and SK Hynix both fell more than 1%, reflecting a rotation within the AI complex from hardware to software names.
- AutoZone (AZO) rose in premarket after the auto parts retailer beat profit expectations but missed revenue forecasts in its fiscal Q4 results before the open — reporting EPS of approximately $54 against the $53.86–$54.10 consensus on revenue of $6.68 billion, slightly below the $6.71 billion estimate. The result reflects a challenging environment for auto parts retailers as consumers stretch vehicle maintenance cycles under pressure from elevated borrowing costs and higher everyday expenses. KB Home (KBH) reports after the close with analysts expecting EPS of $0.89–$0.90 on revenue of $1.29–$1.30 billion — the first major homebuilder read since the Fed's rate hike pushed 30-year mortgage rates above 7%.
- Anthropic confirmed its IPO is slated for November — a development that Nigam Arora at MarketWatch said was among the catalysts driving Monday's equity surge alongside diplomatic proposals around Iran and a new US-Greenland security agreement. The confirmation moves Anthropic's debut from the previously rumored autumn window to a specific month, with the company's annualized revenue having surpassed $11.5 billion earlier in August and investor expectations for a $2 trillion valuation at debut. Vicor Corp (VICR) surged 11.2% in after-hours Monday after raising its Q3 sequential growth guidance from nearly 10% to more than 20%, driven by royalties from a non-exclusive vertical power delivery license — a read on AI data center power management demand. Lockheed Martin (LMT) gained 0.17% in premarket after securing a $1.2 billion Army missile system contract Monday.
- Iran reopening the Strait of Hormuz within seven days emerged as Monday's most market-moving headline — with reports that Tehran was open to restoring transit if Washington eased military pressure sending Brent crude briefly below $99 per barrel before bouncing back toward $101.45 as Trump offered no new concessions. Trump's administration separately announced new sanctions targeting Iranian airlines — a fresh economic pressure measure — while leaving military options on the table. CME FedWatch now shows a 57.6% probability of a rate hike at the October 28–29 FOMC meeting, down modestly from the 60–65% range entering last week's September hike but still elevated enough to keep the tape cautious around rate-sensitive names.
- New York Fed President John Williams and Fed Vice Chair Philip Jefferson are both scheduled to speak Tuesday mid-morning — the first Fed officials to speak publicly since last Wednesday's rate hike and press conference — with markets parsing any signal on whether October is truly live or whether Warsh's "one and done" framing holds. Richmond Fed President Tom Barkin speaks at 1:00 p.m. ET. The Richmond Fed Manufacturing Survey for September prints at 10:00 a.m. ET alongside a 2-year Treasury note auction, which will provide a real-time read on investor appetite for short-duration paper at current elevated yields.
- Asia's session Monday was mixed with a standout divergence between chip and AI names. Japan's Nikkei 225 was closed for the Autumnal Equinox holiday, removing the region's most AI-sensitive index from the tape. South Korea's KOSPI rose approximately 1.5% on continued momentum in Samsung Electronics and SK Hynix — both benefiting from Monday's AMD and Intel surge in US markets — with the Kosdaq little changed. Hong Kong's Hang Seng edged modestly higher on Alibaba strength. China's CSI 300 gained on continued domestic AI investment flows, with mainland investors recording an 11th consecutive day of net purchases via Stock Connect per Saxo. Australia's S&P/ASX 200 slipped 0.46% as iron ore softened and the rate-sensitive property sector faced continued headwinds from the synchronized Fed-BOJ tightening cycle, with the RBA's December hike probability now priced above 90%.
Global Indices:
 Sage Kakkat
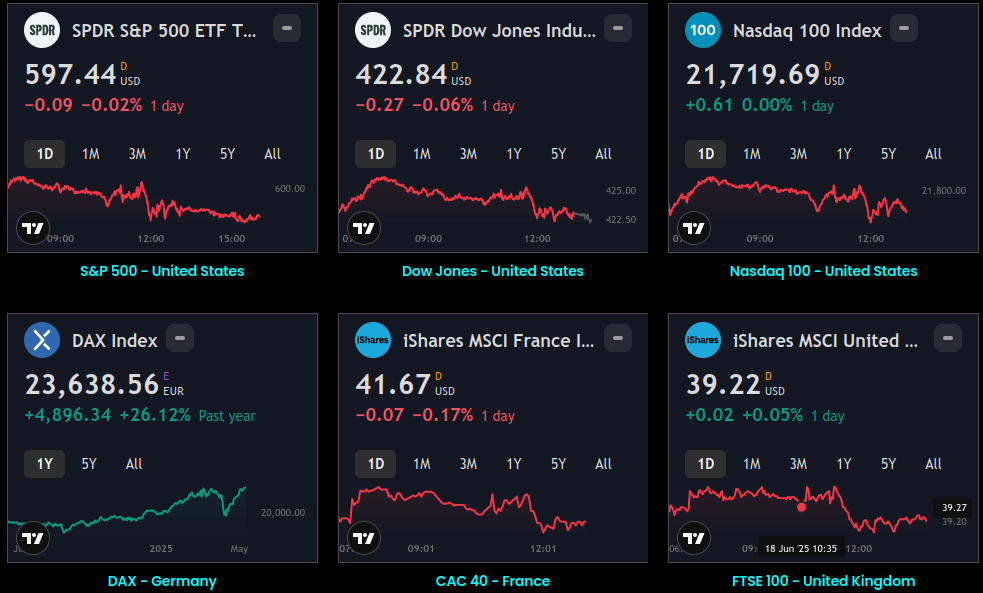
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
