US Stocks open modestly higher to start the second week of Q4 as Friday's dramatic jobs miss — just 29,000 September payrolls against a 90,000 consensus — carries its rate-relief rally into Monday, with the Nikkei jumping 2.5% to a three-month high on AI chip momentum, oil edging lower on Saudi Aramco's surprise price cut and Gulf supply recovery, and Iran's Foreign Minister signaling "no military solution" to the conflict while awaiting a US response through Qatari mediators — a combination that has Polymarket tilting toward a higher open even as the 10-year yield holds stubbornly near 5.28%.
- S&P 500 futures were up 0.14%–0.77% and Nasdaq futures gained 0.38%–1.07% in premarket, while Dow futures rose 0.52% and Russell 2000 futures gained 0.91% — a broad positive setup reflecting continued digestion of the jobs miss that slashed October rate hike odds from approximately 38% to near 20%. Stock futures opened flat Sunday evening before drifting higher overnight as Gulf oil supply news filtered through. The market has remained remarkably resilient given the 10-year yield at 5.28% and Brent crude above $100 per barrel — with strategists at Charles Schwab noting some see "plenty of reasons for a pullback" while others see "more room for a rally to run."
- The session's central economic event is September ISM Services PMI at 10:00 a.m. ET — consensus 55.2, down from August's 55.4. Final September S&P Global Services PMI and Composite PMI also print at 9:45 a.m. ET. The ISM's prices paid sub-component will be closely watched given that services inflation — distinct from the energy-driven goods inflation tied to Iran — has remained stubbornly elevated throughout 2026. A services prices print above 73 (August: 72.6) would add a new inflation worry just as rate hike fears were easing from the jobs miss. ISM employment in services (August: 47.8, below the 50 expansion threshold) will also be read as a broader labor market signal ahead of October 28–29 FOMC.
- The week's other major events: FOMC September meeting minutes on Wednesday at 2:00 p.m. ET — the first look at how close the three dissenters came to forcing an immediate hike — alongside OPEC+ and ECB minutes. PepsiCo (PEP) reports Thursday as the first major consumer staples read of Q4, and Delta Air Lines (DAL) reports Friday alongside preliminary October Michigan consumer sentiment. On Semiconductor (ON) rose 7% Friday after announcing a $5.7 billion all-cash acquisition of Synaptics (SYNA), the chip consolidation story of the week.
- Iran's Foreign Minister Abbas Araghchi said Sunday there is "no military solution" to the conflict with the US — the most constructive diplomatic language from Tehran in weeks — adding that Iran had presented proposals to Qatari mediators and expected a US response Monday. Separately Saudi Aramco CEO Amin Nasser told the Energy Intelligence Forum in London that crude stockpiles are "scarily thin" and warned that until Hormuz fully reopens "pressure at both ends of the barrel will intensify." Houthi rebels claimed missile and drone strikes on Saudi Aramco facilities in Riyadh and Khurais over the weekend, which Saudi Arabia has not confirmed. Brent crude edged slightly lower on the combination of Gulf supply recovery and Saudi Aramco's surprise decision to cut its Arab Light November price to Asian buyers by $3 per barrel — the widest discount since 2020 — a move seen as a bid to reclaim market share from Russian and other competing crudes.
- PTC Inc. rose in premarket after a positive analyst note. GlobalFoundries (GFS) was also among early premarket movers alongside Intel (INTC), which has been in focus following Thursday's Micron-driven AI chip rally and ongoing discussions around its foundry partnership with Apple. Intel Japan jobless rate edged higher to 2.5% per Friday's data, adding a domestic economic note to the BOJ's next policy calculus.
- Japan's Nikkei 225 surged 2.5% to a three-month high as AI-related stocks rallied on softer Fed hike bets following the jobs miss, with semiconductor names including Advantest, Tokyo Electron, and SoftBank Group leading gains. The yen held near 157–158 per dollar despite Japan's Finance Ministry officials toughening their tone on yen weakness — a verbal intervention short of actual FX action, with USD/JPY having been pulled back to around 157 from 159-plus following the jobs data. BOJ policymakers' minutes continue to show broadening internal discussion about scope for faster rate hikes, but the yen's trajectory is doing some of the tightening work independently.
- China's mainland markets — Shanghai Composite and CSI 300 — remain closed for Golden Week National Day holiday through October 7, reopening Wednesday. South Korea's KOSPI was also closed Monday for a public holiday. With two of Asia's largest equity markets off the tape and Hang Seng closed for Hong Kong's National Day holiday, the region's Monday session ran on thin liquidity dominated by Japan, Taiwan, Australia, and India. Australia's services PMI eased as job cuts returned — Australian Treasurer Jim Chalmers separately called the Iran war "an economic disaster" for Australia given its energy import exposure. New Zealand export prices rose, a modest positive for the antipodean economies. India's Nifty 50 and BSE Sensex were modestly lower in Friday's session as elevated oil prices weighed on India's import cost outlook, with the week's full session expected to be more active when South Korea and Hong Kong reopen Tuesday and China Wednesday.
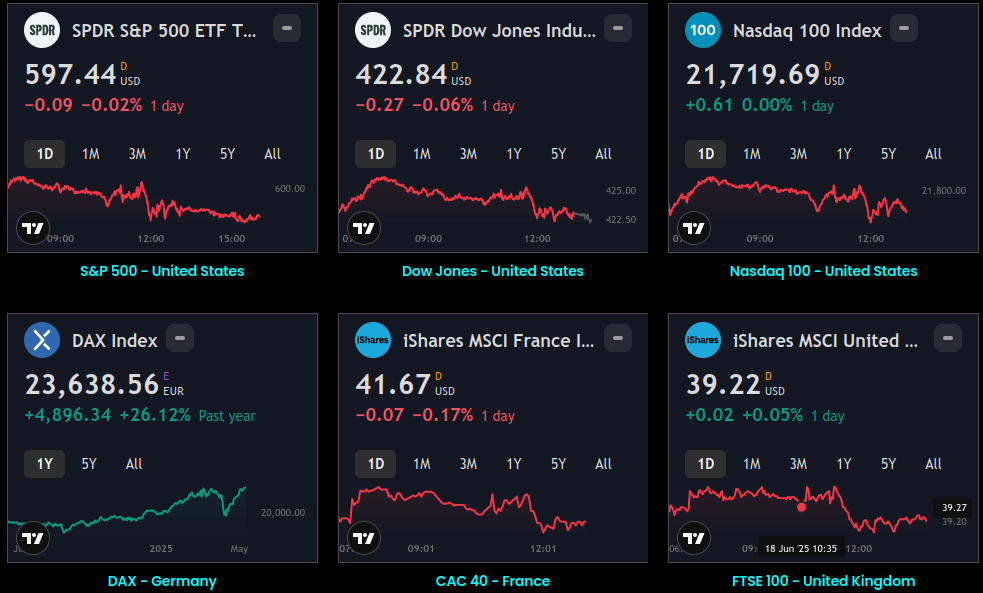
Global Indices:
 Sage Kakkat
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
