US Stocks open modestly higher to close out a brutal four-losing-week stretch for the Dow as Costco's blowout quarter — Q4 revenue of $95.72 billion and same-store sales of 9.4%, both beating consensus — provides a powerful counternarrative to the week's consumer anxiety, even as the 10-year Treasury yield sits at 5.12%–5.225% — its highest since 2007 — and Friday's August durable goods orders and final Michigan Consumer Sentiment at 8:30 a.m. and 10:00 a.m. ET deliver the week's final verdict on whether the economy is cracking under the weight of $100 oil and 4% Fed funds.
- S&P 500 futures rose 0.3% to 7,786, Nasdaq-100 futures advanced 0.5% to 30,913, and Dow futures gained 94–136 points or 0.18%–0.3% to near 51,811 — a modestly constructive setup after Thursday's session in which the S&P 500 closed mixed to slightly lower for a third straight session, leaving it approximately 1.2% below its August record close near 7,799. The Dow is on track for its fourth consecutive weekly loss — a streak not seen since late 2024 — driven entirely by the bond market's relentless climb toward levels not seen in a generation. Polymarket's "S&P 500 Up or Down on September 25" contract dropped to just 39% odds of a higher open in premarket Thursday before recovering to reflect the Costco beat.
- Costco Wholesale (COST) reported Q4 fiscal 2026 results after Thursday's close that beat across the board — revenue of $95.72 billion versus the $94.97 billion estimate, EPS of $6.75 versus the $6.54 consensus, and same-store sales growth of 9.4% with membership fees of $1.85 billion just slightly below the $1.86 billion FactSet consensus. Management guided that capital expenditure growth is expected to slow beyond fiscal year 2027 — a rare spending discipline signal in a week when every earnings metric is being read through the lens of the AI capex excess debate. Shares were little changed in extended Thursday trading as the market digested the beat against the macro headwinds.
- Nike (NKE) is still the week's unresolved consumer read — Bank of America downgraded it to Underperform from Neutral on Thursday with a price target cut to $30 from $47, the latest in a series of downgrades over the past two months from Barclays, Morgan Stanley, Truist, and JPMorgan ahead of its fiscal Q1 report now pushed to October 1. CEO Elliott Hill is midway through a multi-year turnaround plan and separately parted ways with Kylian Mbappé after a 20-year partnership this week — the athlete noted "it was time to change." Scholastic (SCHL) tumbled 12% in premarket on a deep fiscal Q1 miss while Comcast (CMCSA) slid 1.4% after a KeyBanc downgrade and Citigroup price target cut.
- The Trump-Xi summit Thursday at Joint Base Andrews opened with a military display featuring a B-1 bomber flyover and a state dinner attended by Tim Cook, Jensen Huang, and Sam Altman. Treasury Secretary Bessent announced a two-month extension of the US-China trade truce to January 10 — the only concrete bilateral agreement to emerge from the summit. Trade, tariffs, tech restrictions, AI policy, and critical mineral supply chains including rare earths were all on the agenda but yielded no substantive progress beyond the truce extension. Brent crude dipped 0.87% to $102.18 and WTI fell 0.76% to $91.46 on reports that the US and Iran are considering a phased agreement that could reopen the Strait of Hormuz and lift the US blockade on Iranian ports — the most specific structural proposal since the seven-day reopening window a senior Iranian official raised earlier in the week.
- August durable goods orders land at 8:30 a.m. ET — the last major read on business investment before Micron's closely watched fiscal Q4 earnings on September 30 — with the University of Michigan's final September Consumer Sentiment survey at 10:00 a.m. ET. The Michigan print "will test whether consumers have begun to feel the pinch of higher rates" per the week-ahead preview, with a weaker-than-expected reading potentially weighing into Friday's close. The coming week brings Micron earnings September 30 alongside August PCE inflation — the Fed's preferred gauge — and a second-quarter GDP third estimate, making next Tuesday and Wednesday potentially as important as this week's sessions for the rate-path narrative.
- Japan's Nikkei 225 gained 827 points or 1.26% Friday — extending gains to a fifth consecutive session and reclaiming above 66,000 — led by financial stocks including Mitsubishi UFJ up 4%, Sumitomo Mitsui up 3.6%, and Mizuho Financial up 4.2%, as the phased Hormuz deal reports provided some relief. Japan's 10-year JGB yield had climbed to its highest level since 1996 on Thursday, putting significant pressure on the BOJ's capacity to keep financial conditions accommodative. The Nikkei's five-session winning streak is an outlier in a regional picture that remains broadly pressured by the bond selloff. The Chicago futures contract was last at 65,585 and Osaka at 65,490 versus the prior close of 65,513.99 ahead of the session.
- Markets in mainland China and South Korea were both closed for Chuseok — the Korean harvest festival — and China's Golden Week public holiday beginning October 1, reducing regional liquidity significantly. Hong Kong's Hang Seng and the Taiwan TAIEX were both open but traded cautiously amid the Trump-Xi summit overhang and the 10-year yield shock. Australia's S&P/ASX 200 pointed to modest weakness as the RBA's expected rate hike draws closer with September PMIs showing continued services and manufacturing expansion at inflationary input cost levels. German consumer confidence saw what NIM called "a significant setback" in September as rising energy prices dragged income expectations to their lowest since April — a symptom of the Iran war's impact on European household purchasing power that adds to the global stagflation concern Warsh's Fed is now navigating.
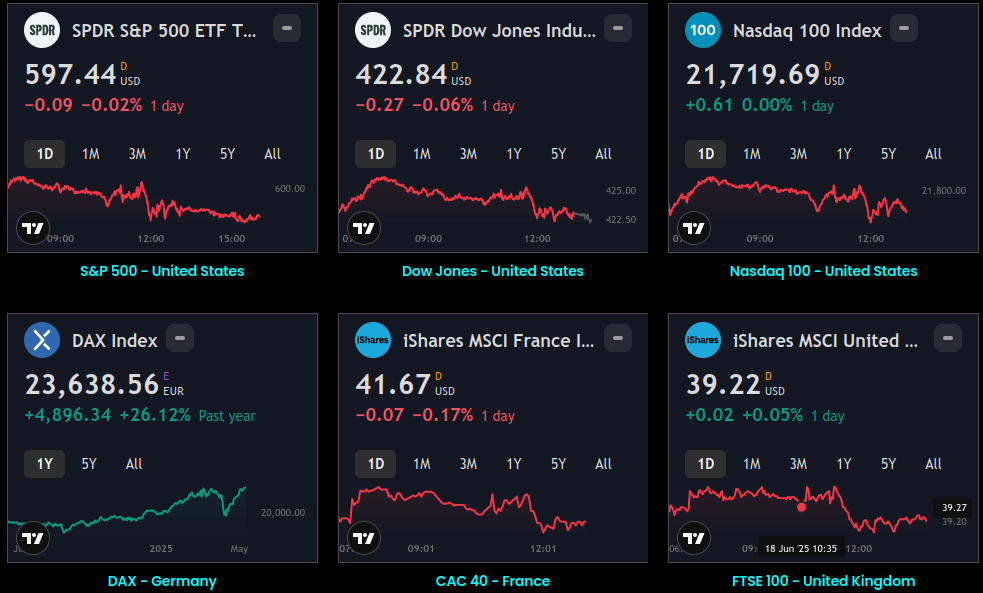
Global Indices:
 Sage Kakkat
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
