US Stocks open mildly positive heading into the week's most data-heavy session as a Trump-Iran three-hour meeting on the sidelines of the UN General Assembly — described by Trump as "a very good meeting" — extends Brent crude's decline to a sixth consecutive session, pushing it back below $100 for the first time since early September, pulling the 10-year Treasury yield back below 5%, and sending the Nasdaq Composite to back-to-back record closes even as the Dow and broader cyclical tape lag.
- Dow Jones futures were down 0.32% to 52,112 in premarket but the index is expected to open approximately 250 points above Tuesday's close of 51,863.69, while S&P 500 futures edged down 0.11% to 7,822 and the Nasdaq 100 futures were marginally positive — a mixed setup that reflects continued tech-versus-cyclical bifurcation. Tuesday's full session ended with the Nasdaq Composite gaining 0.45% to 27,244.27 to set a new record close — its second straight record high, the first back-to-back record for the index since June — while the S&P 500 finished essentially flat at 7,764.64 and the Dow fell 0.36% to 51,863.69. The VIX fell 4.44% to 14.21, its lowest reading of the year per Fortune, signaling that options markets have substantially de-risked from September's peak anxiety.
- The Trump-Iran meeting at the UN General Assembly in New York is the dominant geopolitical development. A senior Iranian official confirmed that Tehran can reopen the Strait of Hormuz within seven days if the US eases military pressure and lifts its blockade on Iranian ports — the most concrete diplomatic timeline offered since the conflict began February 28. Trump's description of the three-hour sideline meeting as "very good" is the most constructive language he has used toward Iran in weeks. Brent crude's November contract settled at $99.25 per barrel Tuesday — down $1.09 — as Saudi Arabia's East-West pipeline resumed operations following last weekend's drone attacks and vessel activity through the Strait improved marginally. WTI crude was near $94 a barrel in Wednesday's early trading.
- The September flash PMIs at 9:45 a.m. ET are Wednesday's central economic event — the first real-time activity read in the post-rate-hike environment. S&P Global will release both Manufacturing and Services flash estimates simultaneously, with markets watching for whether the Fed's September hike and $100-plus oil through most of the month have begun to crimp business activity. Capital.com's Daniela Hathorn said the oil decline has provided "much-needed relief from the inflation and rates concerns that have dominated September," with the 10-year yield's retreat below 5% stabilizing bond markets and giving equities room to run. CME FedWatch showed the October rate hike probability at 57.6% — elevated but off its peak — with the Iran diplomatic progress the single most important variable that could pull that probability lower if it translates into an oil price decline below $90.
- Cintas (CTAS), Paychex (PAYX), General Mills (GIS), and Cracker Barrel (CBRL) all report before the open. Cintas, with a $79.3 billion market cap, is closely watched as a barometer for business services demand — analysts expect EPS of $1.35–$1.36 on revenue of $2.98 billion. Paychex provides a direct read on small-business payroll health, with consensus at $1.32 EPS on $1.63 billion revenue. General Mills offers the consumer staples and food cost inflation picture, while Cracker Barrel provides the restaurant consumer read. Tomorrow's calendar is busier: Costco (COST) and Nike (NKE) both report Thursday, which analysts flagged as "critical in determining the health of the US consumer." Micron Technology's fiscal Q4 report on September 29 is already casting a shadow over the semiconductor sector per StockMarketWatch.
- IonQ (IONQ) jumped 11.35% in premarket Tuesday after the quantum computing company announced the development and testing of a real-time quantum error correction decoder — a significant technical milestone in making quantum computing commercially practical. Alibaba surged roughly 3% in Hong Kong Tuesday after unveiling the Zhenwu V900, its next-generation AI chip delivering three times the performance of its May predecessor, alongside plans to sharply expand its data center footprint at the Apsara Conference in Hangzhou. Twilio (TWLO) has gained 99.18% year-to-date through Tuesday, reaching $284.53 — one of the S&P 500's stealth outperformers, driven by AI-powered customer engagement platform demand.
- Japan's Nikkei 225 returned from a three-day holiday closure — markets were shut Monday through Wednesday for Autumnal Equinox — with FXStreet noting analysts expected "a strong reopening in Japan tomorrow, with another move lower in crude, calm conditions in rates and Treasuries, and the Nasdaq cash and futures markets printing record highs." The index rose 1.38% on Wednesday, its best session in two weeks, as chip equipment names led the catch-up rally. South Korea's KOSPI was marginally positive at 7,020–7,023, with the Kosdaq adding 1.12% and Taiwan's TAIEX rising 0.80% to 48,181 — both extending the Nasdaq-led semiconductor recovery. Australia's S&P/ASX 200 edged up 0.05% to 8,761.90, with Australia's flash September PMIs due later Wednesday evening — a key data point ahead of the RBA's expected rate hike, with September data arriving days before the decision. China's Shanghai Composite slipped 0.18% to 3,944.87 and the Shenzhen Component fell 0.38%, while Hong Kong's Hang Seng declined 0.84% to 24,876.17 on profit-taking in tech names even as Alibaba's chip announcement lifted sentiment in select names. India's Nifty 50 added 0.44%.
Global Indices:
 Sage Kakkat
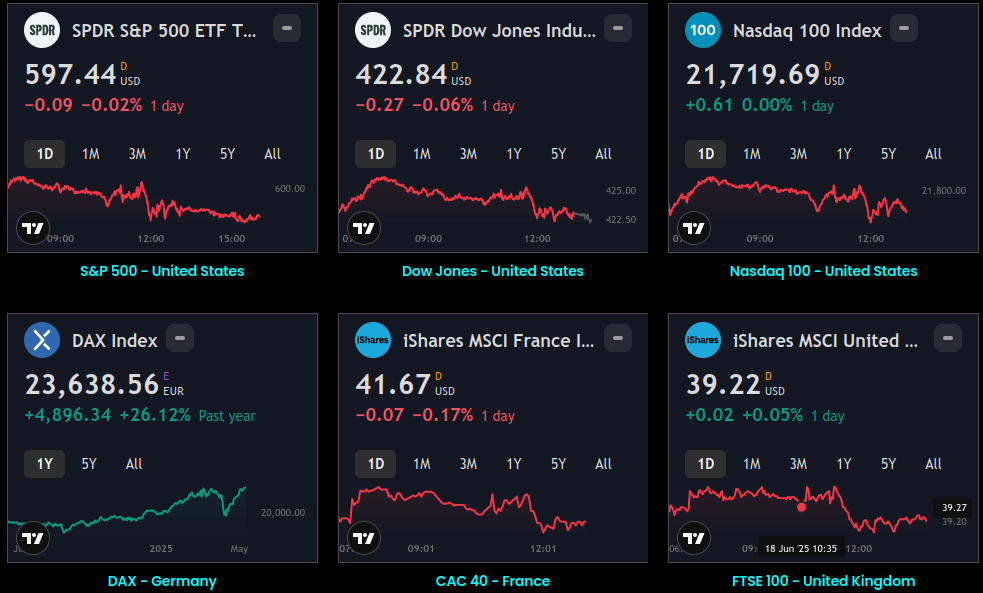
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
