US Stocks open higher to continue the week's rally as Nvidia broke above $6 trillion in market value for the first time Monday, Wall Street's record-setting Nasdaq close sets a bullish tone, and a $60 billion Broadcom-led debt deal tied to Anthropic's Google TPU lease and a $1 billion Constellation Energy-Google nuclear power agreement provide dual AI infrastructure spending catalysts — even as Deutsche Bank warns bonds and equities are pricing "very different outcomes" with 10-year yields at 2007 highs and the Nasdaq near record highs simultaneously.
- S&P 500 futures were higher in premarket as stocks extended Monday's gains — in which the Nasdaq Composite set a new record close, the S&P 500 climbed, and SpaceX (SPCX) rose 0.91%, Nvidia (NVDA) gained 0.43%, Constellation Energy (CEG) jumped 14.08%, and AMD advanced 3.58%. Futures maintained their upward bias into Tuesday's open on the Nvidia $6 trillion milestone and the broad AI infrastructure spending acceleration confirmed by Monday's nuclear and chip deal headlines. Tuesday's earnings slate is light: RPM International (RPM, est. EPS $1.95 on $2.22 billion revenue) and Lamb Weston (LW, est. $0.589 on $1.65 billion) before the open, and Constellation Brands (STZ, est. EPS $3.61 on $2.54 billion), Penguin Solutions (PENG), and Neogen (NEOG) after the close.
- Nvidia's market cap broke above $6 trillion for the first time on Monday, helped by the $150 billion buyback expansion announced September 28 and a fresh Morgan Stanley upgrade — making Nvidia the first company to exceed that market value in history and cementing its position as the world's most valuable company by a widening margin. Wall Street banks simultaneously launched a record $60 billion debt syndication package tied to Anthropic's lease of Google-designed TPUs supplied through Broadcom — the largest single AI infrastructure financing deal ever assembled — providing a direct revenue catalyst for Broadcom's custom AI chip business even as Anthropic's $518 billion in planned compute obligations remain the central question of the AI bubble debate.
- Constellation Energy (CEG) surged 14% Monday — its biggest single-session gain since January — after reports that it is nearing a multi-year nuclear power supply deal with Google valued at approximately $1 billion, extending the hyperscaler-nuclear theme that has driven nuclear power stocks throughout 2026. The Calvert Cliffs 20-year Amazon deal announced last week and the Google Constellation agreement together confirm that AI data center power procurement has shifted from short-term energy contracts to multi-decade baseload commitments — a structural change that amounts to a de facto endorsement of nuclear as the AI economy's preferred power source. GE Vernova (GEV) was up in premarket following its Jefferies upgrade.
- Microsoft (MSFT) rose 0.5% in early premarket after Melius Research upgraded the stock to Buy with a $665 price target. Rocket Lab (RKLB) was in focus after Cathie Wood's ARK Investment called the company's opportunity "enormous," particularly as SpaceX looks toward eventually retiring Falcon 9 and Rocket Lab positions itself as the successor small-launch vehicle. The Trump administration's stated focus on lower-cost autonomous defense technology was also flagged as a potential additional catalyst for defense and drone stocks. Nokia (NOK) appeared in the premarket movers list without a specific catalyst confirmed.
- Deutsche Bank's warning that bonds and equities are pricing very different outcomes is the week's most prominent macro risk note. US 10-year yields near 5.28% — their highest since 2007 — alongside the French-German spread posting its largest weekly rise since 1990, while US equities sit near records with what the bank described as "little sign of stress," present what it characterized as an unstable configuration: either the stress eases quickly or risk assets must reprice for weaker growth. The FOMC September meeting minutes on Wednesday at 2:00 p.m. ET will be the week's pivotal event — revealing exactly how the three dissenting members framed their case for an immediate hike on July 29, and whether the majority view has shifted since the September jobs miss cut October hike odds to approximately 20%.
- Japan's Nikkei 225 climbed above 70,000 for the first time, closing at 70,683.98 — up 1.1% — a historic milestone for the index that reflects Japan's extraordinary 2026 performance: up 32.6% year-to-date and 49.8% year-over-year, driven by AI chip equipment names, SoftBank, and the structurally weaker yen boosting export earnings. The 70,000 level had been flagged by analysts as a key psychological barrier since the Nikkei crossed 69,000 in late September. USD/JPY held near 158 as Japanese Finance Ministry officials continued verbal intervention against yen weakness without triggering actual FX purchases.
- Hong Kong's Hang Seng gained 1.0% to 24,280.56 as mainland Chinese markets remained closed for Golden Week. South Korea's KOSPI fell 0.9% to 6,941.39 as semiconductor heavyweights Samsung Electronics and SK Hynix both declined — a notable divergence from Monday's regional AI rally driven by specific chip stock profit-taking rather than macro deterioration. Mainland China's Shanghai Composite and CSI 300 remain closed through October 7, reopening Wednesday. Australia's ASX 200 advanced. European stocks extended their recovery, with the Stoxx 600 moving higher in early Tuesday trade. Oil retreated below $100 per barrel — Brent edging lower — as Treasury yields eased modestly but remained at historically high levels, and Iran's Foreign Minister's "no military solution" signal from Sunday continued to provide diplomatic cover for the oil pullback.
Global Indices:
 Sage Kakkat
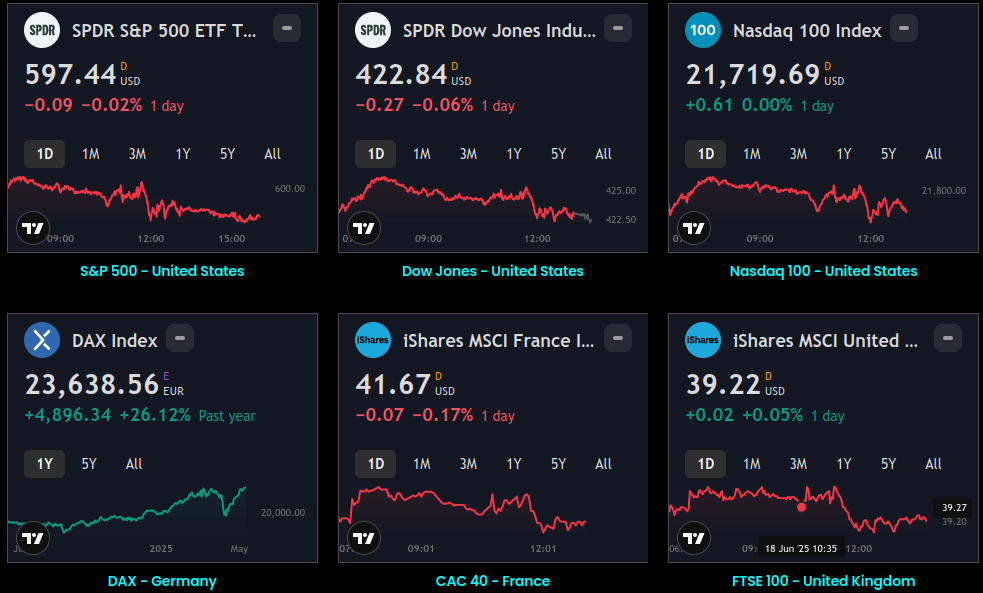
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
