US Stocks open in cautious wait-and-see mode with all eyes on the FOMC September meeting minutes at 2:00 p.m. ET — the afternoon release that will either confirm or upend the market's current working assumption that October 28–29 is a pause, not a hike — even as Iran mocked the US economy in a state media broadcast overnight, Brent holds near $101, and the S&P 500 and Nasdaq both eased from Tuesday's record highs.
- S&P 500 futures fell 0.25%–0.61% and Nasdaq-100 futures declined 0.70% as stocks eased from record levels, with Polymarket showing 62% odds of a higher open before futures turned negative on Iran overnight headlines. Tuesday's session saw the S&P 500 slip 0.25% to 7,799 and the Nasdaq ease 0.3% from consecutive record closes, as concerns about high bond yields returned to the forefront and the 10-year Treasury yield climbed toward 5.31%. The 10-year Treasury note auction at 6:00 p.m. BST / 1:00 p.m. ET is Wednesday's first major rates test before the minutes — a weak auction would pressure yields higher ahead of the 2:00 p.m. ET release.
- The September FOMC minutes land at 2:00 p.m. ET — covering the unanimous 9-0 vote on September 16 to hike 25 basis points to 3.75%–4.00%, the first rate increase in three years. Markets are pricing only a 22% probability of an October hike — down from approximately 51% one week earlier following the September jobs miss — making the minutes the pivotal event that will determine whether that pricing is correct or dangerously complacent. Investing.com laid out the two scenarios: a dovish read showing broad support for patience post-jobs-miss would push Treasury yields lower and extend the Nasdaq's record run; a hawkish majority read revealing that many officials viewed September as merely the first step would revive yield pressure and weigh on growth stocks at elevated valuations. Dallas Fed President Lorie Logan said on October 1 the target range may need to rise "an additional 50 basis points or more" — if the minutes show her view was widely shared, October becomes live again. The post-release reaction confirmed the hawkish lean: FOMC officials saw another hike as likely appropriate in 2026, sending the S&P 500 and Nasdaq lower after 2:00 p.m. ET.
- Iran's state media broadcast an overnight segment mocking the US economy — citing the 10-year Treasury yield at multi-decade highs, the jobs miss, and what it characterized as a "structurally weakening" American labor market — an unusual move that analysts read as Iran attempting to project strength as it awaits the US response to its Qatari-mediated ceasefire proposal. Iran's Foreign Minister reiterated that "no military solution" exists while simultaneously warning that Iran's patience has limits. Brent crude held near $101 per barrel and WTI near $94 as the diplomatic signal and oil inventory data — the API reported a 2.09 million barrel crude draw for the week ending October 2 — provided a floor under oil prices even as the broader diplomatic tone remained more constructive than at any point since September's escalations.
- China's mainland markets reopen Thursday after the final day of Golden Week today — with the Shanghai Composite and CSI 300 having been closed since September 30. Analysts flagged potential catch-up volatility on the first trading day back, as Chinese domestic investors will be repricing for the Fed's September hike, the jobs miss, the Nikkei breaking 70,000, and a week of AI infrastructure spending confirmations (Broadcom $60 billion Anthropic deal, Constellation Energy Google nuclear deal, Nvidia $6 trillion market cap) that all occurred while they were off the tape.
- Levi Strauss (LEVI) and Applied Digital (APLD) both report after today's close — the only notable earnings of the session. Levi is expected to report quarterly EPS of $0.36 on $1.62 billion revenue — a read on consumer discretionary spending in a high-rate environment — while Applied Digital, an AI cloud infrastructure company, is expected to show a quarterly loss of $0.29 per share on $126.47 million revenue, providing a secondary AI data center demand signal after the week's larger Micron and Broadcom headlines. Consumer credit data for August is due at 3:00 p.m. ET.
- Japan's Nikkei 225 was lower in early Wednesday Asian trade — pulling back modestly from Tuesday's historic close above 70,000 at 70,683.98 — as Iran overnight headlines and the FOMC minutes overhang kept investors cautious. Hong Kong's Hang Seng also traded lower. South Korea's KOSPI was mixed as chip stocks gave back some of the week's gains following Samsung Electronics and SK Hynix declines on Tuesday. Bitcoin fell 1.9% to approximately $83,694 as the dollar index held above 102 and 10-year yields pressed higher, confirming that crypto is trading as a liquidity-sensitive risk asset rather than an inflation hedge in the current environment. The 10-year yield's failure to pull back meaningfully despite the October hike odds dropping from 51% to 22% is what Deutsche Bank flagged as the market's central structural tension — bonds and equities remain in direct disagreement about what comes next.
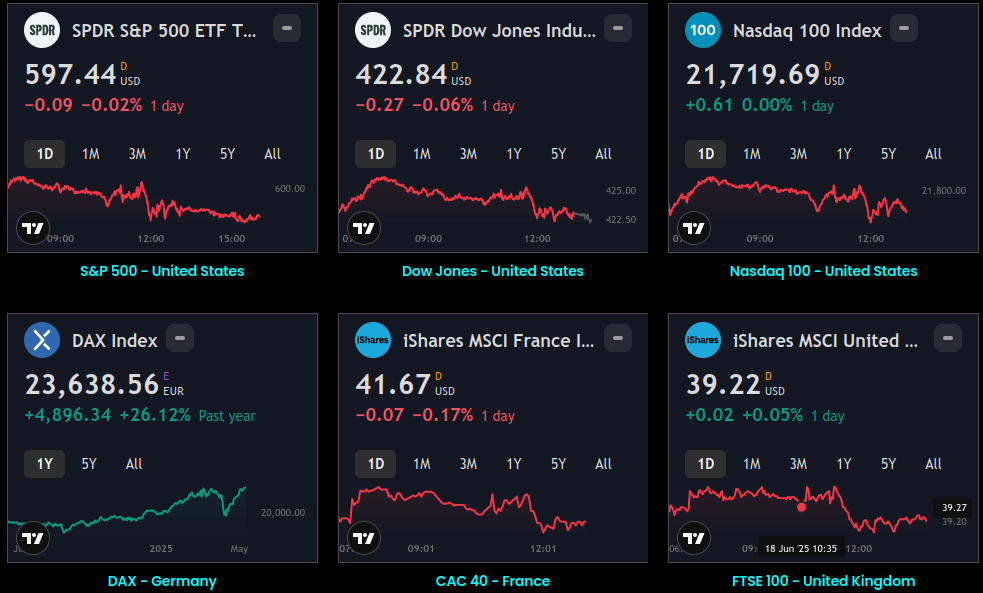
Global Indices:
 Sage Kakkat
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
