US Stocks open in muted Columbus Day trading — equity markets are open but the Treasury bond market is closed, most banks are shut, and trade settlement will be delayed by one day — with Brent crude retreating toward $103.90 after Trump announced a Russia-diesel deal that temporarily waives Iranian sanctions pressure, the KOSPI cratering 3.4% after returning from its long weekend, and the market holding its breath for the week's two defining events: major bank earnings beginning Tuesday and September CPI on Wednesday.
- Dow Jones futures rose 0.06%, S&P 500 futures gained 0.12%, and Nasdaq futures were flat to marginally lower in early Monday trading — a typically thin Columbus Day setup as the absence of the bond market removes a key price discovery mechanism and most institutional desks are on reduced staffing. The S&P 500 closed last week up 1.2%, the Dow gained 0.9%, and the Nasdaq added 0.6% — the first week of positive weekly closes for all three since mid-September — driven by the tech rebound from the OpenAI revenue shock, Humana's Medicare star ratings surge, and Trump's midterm pre-election peace pledge on Iran. Brent was trading near $103.90, down 0.8%, and WTI near $90.70, down 1.3%, providing some relief from last week's $106 intraday highs.
- Trump announced a deal for Russia to supply diesel to the United States and waived sanctions on Russian diesel imports through April 2027 — a supply-side oil price management maneuver that pulled crude off its recent highs even as Houthi strikes on Saudi Arabia, including a claimed missile attack on Riyadh's King Khalid International Airport, kept supply risk alive. JPMorgan's global economics head Bruce Kasman noted that "oil prices remain higher than we had assumed as shipping costs have soared, and product prices are even higher" — a pre-earnings warning from one of the banks reporting Tuesday. Hurricane Isaias separately came ashore near Destin, Florida as a Category 2 storm Friday, shutting in approximately 72% of Gulf of Mexico oil output and contributing to last week's Brent settlement at $104.72.
- The week's four dominant events in order: JPMorgan Chase, Goldman Sachs, Citigroup, Wells Fargo, Johnson & Johnson, and UnitedHealth all report before Tuesday's open — the official start of Q3 2026 bank earnings season, providing the first systemic read on consumer credit quality, loan demand, and net interest margin in the post-hike, high-oil environment. Wednesday's September CPI at 8:30 a.m. ET is consensus at 0.6% month-on-month and 3.6% year-on-year — a sharp acceleration from August's 3.4% — almost entirely driven by oil's surge through September, which Brent closed at $104.72. Tickmill's Munnelly noted that "broader pass-through into services, logistics or goods prices would challenge market confidence in an October pause." TSMC reports Thursday at its earnings conference at 2:00 a.m. ET / 7:00 a.m. BST — the week's key AI chip demand read after the recent OpenAI revenue setback — with investors focused on AI accelerator demand, 2nm progress, and capital expenditure guidance. Fed Chair Kevin Warsh speaks in Bangkok at the IMF/World Bank Annual Meetings Thursday night.
- Apple holds its "Welcome Home" event in New York Tuesday at 9:00 a.m. ET — confirmed to center on home products including an expected updated Apple TV and potentially smart home hardware — in what Macworld and others have framed as Apple's push into the AI-enabled home ecosystem. The event lands simultaneously with the bank earnings deluge, creating an unusual morning of overlapping catalysts. Separately, the Nobel economics prize is announced today at 5:45 a.m. ET.
- South Korea's KOSPI cratered 3.38% to 6,402 on Monday — its worst single session since early October — as the index returned from its long Chuseok-related holiday weekend to catch up with last week's global tech sell-off, foreign selling, and Middle East worries. Samsung Electronics and SK Hynix both fell sharply as the combination of the OpenAI revenue shortfall, the hawkish FOMC minutes, and $106 Brent that hit late last week all landed simultaneously on the Korean tape. Japan's Nikkei 225 was closed for Health-Sports Day — a national holiday — with the index having closed Friday at 68,512.30 after a weekly gain of approximately 2.9%. Hong Kong's Hang Seng was barely changed at 0.07% higher at 24,230 and the Shanghai Composite slipped 0.16% to 3,808. Australia's ASX 200 rose 0.76% to 8,783, with energy producers gaining on elevated oil prices. India's Nifty 50 fell 0.48%.
Global Indices:
 Sage Kakkat
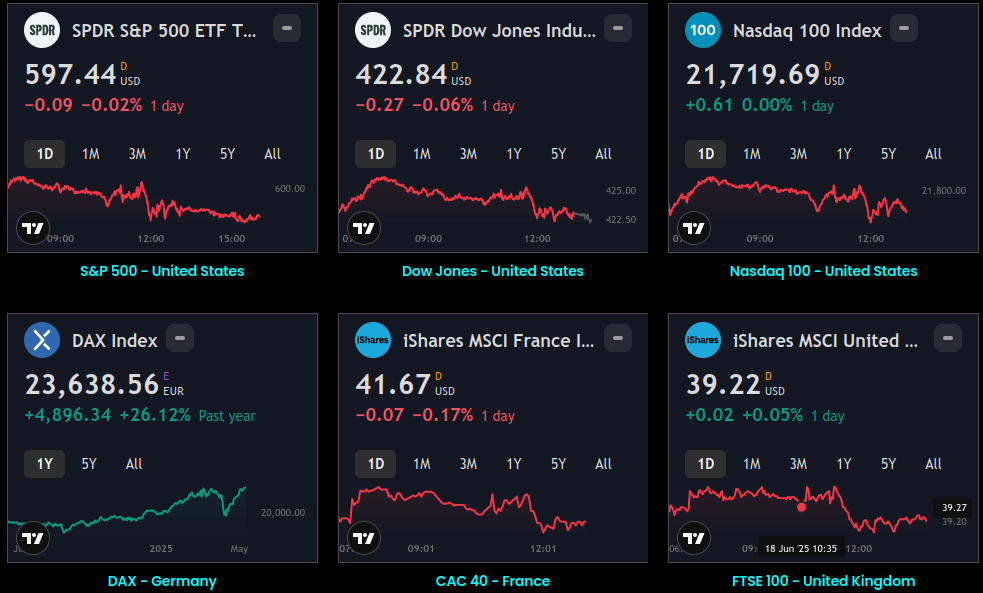
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
