US Stocks sold off hard on Thursday as AI spending fears came back within hours of the earnings meant to bury them: the Nasdaq fell 2.6% for its worst day since June and the S&P 500 lost 1.2% for its worst day since July. Meta fell nearly 7% as it raised capex, burned cash and created a new share class to help pay for it, Tesla cut its capex plan, and Lam Research plunged nearly 12% on supply constraints. Oil climbed to its highest since May with Brent above $112, and Asia sold off first and harder, with Hong Kong at a four-month low and China's CSI 300 at the edge of a bear market. The market is now pricing how AI gets funded, not whether demand exists.
- The S&P 500 fell 93.74 points to 7,663.43 and the Nasdaq Composite dropped 694 points to 26,008.86. The Dow edged up 11.89 points (0.02%) to 52,867.98 and the Russell 2000 gained 0.11% to 2,784.03, so blue chips and small caps held while AI-heavy tech absorbed the damage. Wednesday's rally in SpaceX, Super Micro and Nvidia reversed: SpaceX gave back more than half of its post-earnings gain as a lockup expiry freed up to 1.3 billion shares, Nvidia and Micron fell, and CoreWeave lost 7.8% as worries over its AI-chip debt flared again. Spotify bucked the trend with a 9% gain on improved margins.
- Meta (META) fell 6.98% despite beating on revenue, with Q3 sales of $64.60 billion up 26% and Q4 guidance of $73–76 billion above estimates. The market focused on funding: 2026 capex was narrowed to $135–145 billion, free cash flow turned negative (the first cash outflow in more than a decade), future lease and contract commitments rose to about $825 billion from about $700 billion in July, and profit fell short of expectations. Meta also created a non-voting Class C share, issued as a one-share dividend effective January 19, 2027, which works like a 2-for-1 split and lets it raise money without diluting control. Its five-year credit default swaps hit a record near 119 basis points intraday.
- Tesla (TSLA) fell 3.08% after beating on profit but missing on revenue and cutting its 2026 capex plan to about $20 billion, a cut of roughly $5 billion that the market read as a growth cut. Spending is set to rise in 2027 and 2028 on Optimus, Cybercab and Terafab. Tesla also booked a $140 million mark-to-market loss on its SpaceX stake, and Bloomberg reported the two companies are targeting a merger announcement in the first half of 2027.
- Lam Research (LRCX) plunged 11.76% even though revenue of $8.22 billion and EPS of $2.20 beat estimates, because it warned of supply-chain and clean-room constraints into 2027, gave an October–December outlook that was not bigger than expected, and signaled a falling China revenue share. That dragged chip designers down, with AMD off 8.10% and Marvell off 8.70%, and Tokyo Electron fell 6.9% in Tokyo. Wells Fargo traders said Jensen Huang's comments about a scarcity of capital were also spooking markets and reigniting concern that credit markets are full on AI risk appetite.
- Oil pressured everything, with Brent above $112, the highest since May, on Iran war worries and Hormuz risk. Bitcoin slipped toward $82,000 and gold and silver declined. Fed officials remain in their blackout period ahead of the October 28 decision, so earnings and oil are the main drivers. In Europe, Germany's DAX fell 1.07% to 25,371.75 with Siemens Energy down 8.6% and Infineon down about 6%, and French 10-year yields were reported to have risen above US 10-year yields for the first time since 2013. Brazil's Ibovespa dropped 1.15% ahead of Sunday's runoff.
- Asia led the selloff despite Wednesday's positive Wall Street lead. Japan's Nikkei 225 fell 2.65% to 62,907.84 (down 1,713 points), a near three-month low and its first close below 63,000 in about three months, as Lam's after-hours plunge hit chip equipment names. South Korea's KOSPI dropped 3.52% to 5,533.77, with SK Hynix down 5.49% and Samsung down 4.03%, even as the Bank of Korea held rates as expected. Taiwan lost about 2%, and MSCI Asia ex-Japan hit a three-month low.
- Greater China fell hardest. Hong Kong's Hang Seng dropped 3.03% to 22,934.68, a four-month low, on tech selling and rumors of mainland tax sales, with Lenovo and Hua Hong Semiconductor each down about 7% and CATL extending its losing streak to a seventh day. China's CSI 300 shed 1.8% to 4,036.30, entering bear-market territory (down 20% from its high), and the Shanghai Composite also fell on Middle East uncertainty and semiconductor selling.
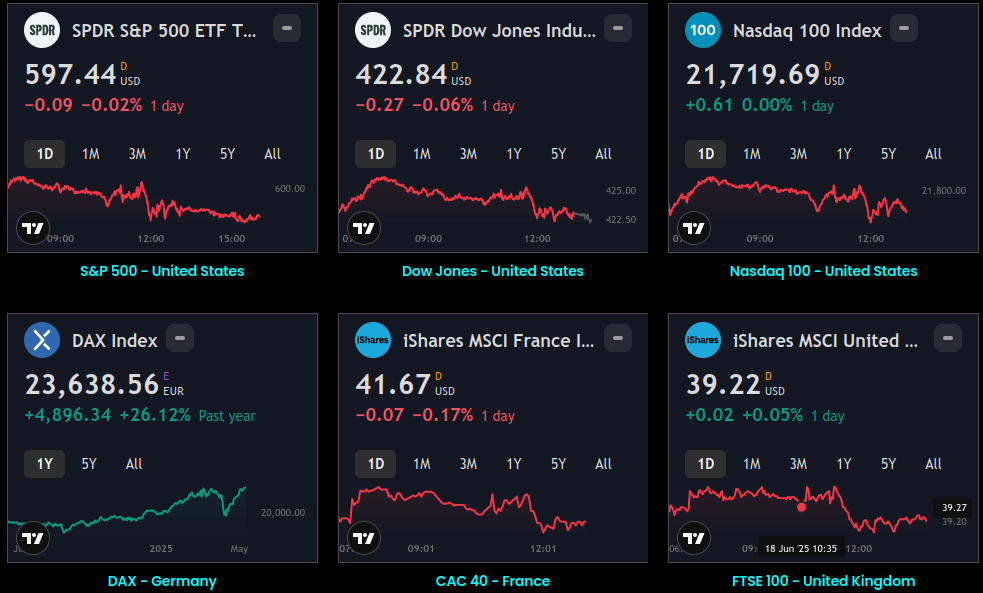
Global Indices:
 Sage Kakkat
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
