US Stocks opened lower on Friday as oil pushed to a five-month high and the sell-off in AI and chip stocks stayed in focus. Brent touched about $115 on Houthi attacks in Saudi Arabia, the highest since early May, and Trump invoked the Defense Production Act for oil with pump prices biting 12 days before the midterms. Dow futures fell as much as 0.9% on the oil spike, American Express beat on profit but announced a 5% workforce cut to "prepare for AI," and the Nasdaq is on track for a rare third 2%-plus drop in seven days. Asia sold hard in the morning and then mostly clawed back, with Korea's KOSPI reversing from a 4% drop to a small gain.
- S&P 500 futures fell 0.25–0.5% (to about 7,666–7,685) and Dow futures fell 0.6–0.9% (to about 52,600–52,750). Nasdaq futures were roughly flat after Thursday's 2.6% plunge, and by the open stocks were lower. The S&P 500 had been about flat for the week after Thursday's 1.2% drop and the Nasdaq down about 0.5%. Bespoke noted this would be the first time the Nasdaq 100 has had three 2%-plus drops in a seven-day span since April 2025. The 9:45 a.m. ET flash PMIs and 10:00 a.m. final University of Michigan sentiment are the data on the calendar.
- Oil led the move, with Brent at $114–115 (the highest since May 4) and WTI near $100–101. Houthi attacks on Saudi Arabia drove the rise, and Thursday's 4% jump already took crude to a five-month high. Gold fell below $4,000 for the first time since July and silver sank below $55, its lowest close in almost a year, as rate worries and dollar strength offset haven demand. Bitcoin stayed muted below $82,000.
- American Express (AXP) reported Q3 EPS of $5.42 against $4.50 expected and raised its full-year forecast, but revenue was slightly light and CEO Stephen Squeri said it plans to cut about 5% of its global workforce to prepare for AI. The stock fell about 2.9% in premarket. Robert Half jumped 8.8% on a beat, and SLB and Infosys also report. In tech, Intel rose about 3% on an FCC waiver, SpaceX gained about 2% to near $148 after Thursday's lockup-driven slide, and SK Hynix scrapped its planned Solidigm IPO. OpenAI was reported to be close to raising up to $30 billion at a $1.25 trillion valuation, led by UAE investors.
- In rates, Treasuries rallied into Thursday's $26 billion 5-year TIPS auction, which cleared at the highest yield since October 2023 (2.367%) before the rally trimmed yields. Breakeven inflation rates fell as growth risks replaced inflation fears, and December fed funds contracts no longer fully price another 2026 Fed hike. Fed officials remain in their blackout period ahead of the October 28 decision. European stocks opened lower on French debt worries and bond-yield pressure.
- Asia opened sharply lower on the chip rout, then recovered through the day. South Korea's KOSPI fell as much as 4% intraday (it hit a low of 5,306) but closed up 0.30% at 5,550, and the Kosdaq fell 1.62% to 751.69. Even so, the KOSPI is on course for a fourth straight weekly loss, with a drop of more than 4% for the week. Japan's Nikkei 225 swung from a 2.3% loss to close down 0.34% at 62,693, with defensive names Kao, Secom and Sekisui House outperforming. Taiwan's markets were closed for Typhoon Champi.
- Japan's September CPI rose to 2.1% from 1.9%, the highest since December 2025, with core also at 2.1%, just above the BOJ's 2% target. That revived bets on another BOJ hike, and the yen firmed to about 156 per dollar. Hong Kong's Hang Seng rose 0.69% to 23,093 after Thursday's bear-market slide, led by a 2.05% jump in the Hang Seng Tech index. China's Shanghai Composite recovered to about 3,690 (up about 32 points) after being down 1.3% earlier. The CSI 300 entered a bear market Thursday, having lost $2.4 trillion since its May peak. Indonesia's JCI rose 0.95% to 5,439.
Global Indices:
 Sage Kakkat
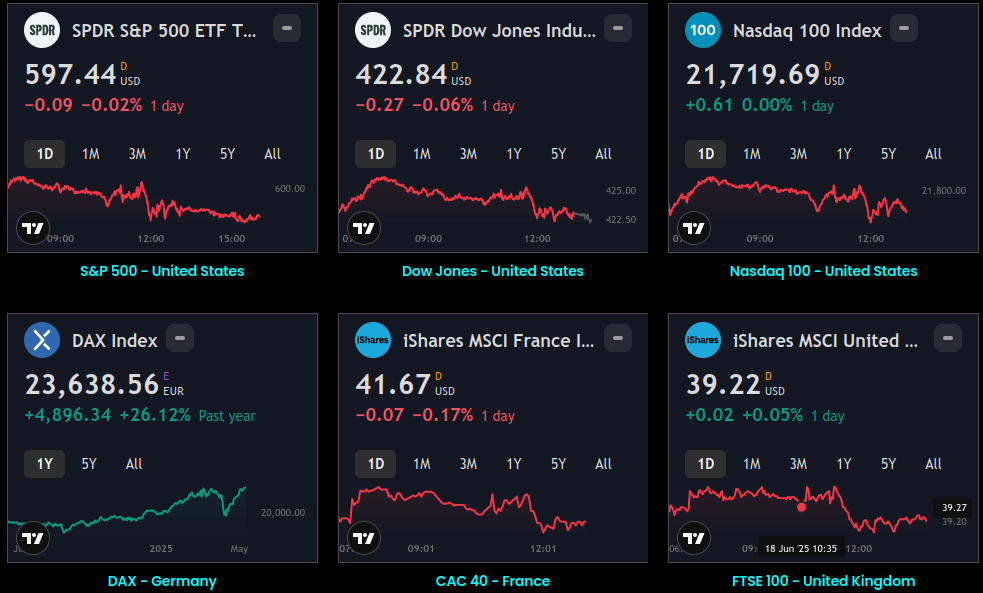
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
