US Stocks opened higher on Tuesday as the AI rebound from Anthropic's IPO filing carried into the day, with Nasdaq 100 futures up about 0.6% and S&P 500 futures up about 0.4% before the bell, while the Dow lagged as Coca-Cola and Boeing reported. The Fed starts its two-day meeting, with economists expecting a "hawkish pause" Wednesday, and oil eased on Iran peace-talk hopes. Asia led the move: Korea's KOSPI rose 3.1% (after a brief sidecar halt) on a stronger-than-expected Q3 GDP, Japan's Nikkei gained 1.7% on chip names, and China and Hong Kong lagged.
- S&P 500 futures rose about 0.4%, Nasdaq 100 futures about 0.6% and Dow futures about 0.4% as of 8:30 a.m. ET, after a mixed, slightly lower early session overnight. Stocks opened in the green, and Polymarket showed 67% odds of an up open. The rally follows Monday's closes of 7,676.77 on the S&P 500 (+0.70%), 26,169.38 on the Nasdaq Composite (+0.82%) and 52,361.58 on the Dow (+0.28%). SK Hynix's US-listed shares rose more than 3% on reports it is weighing a special dividend of about ₩16 trillion ($12 billion), and Celestica surged more than 15%.
- The Fed's two-day meeting begins Tuesday, with the decision and Chair Warsh's press conference on Wednesday. The central bank is widely expected to hold at 3.75–4.00%, with traders looking for clues on whether a hike is still coming before year-end. The risk is that a hawkish signal pressures high-valuation tech, while an in-line decision shifts focus back to earnings and the returns on AI spending. Markets are positioned for a hawkish pause rather than a surprise.
- Earnings are heavy. Coca-Cola raised its outlook but reported slowing demand in North America, and its stock slipped; Boeing, PayPal and UPS also reported before the open, and SoFi jumped after beating and raising guidance. After the close come Visa, Robinhood, Seagate and NXP, with SK Hynix's results on Wednesday and Samsung's Thursday (Samsung has flagged an operating profit up nearly eight-fold). Meta traded near $629 support after a $37.5 billion stock sale at $625 tied to its new share class.
- Anthropic's S-1 remains the market's focus: ticker ANT on Nasdaq, about $16.3 billion of first-half 2026 revenue and an $80.7 billion net loss, mostly accounting charges. Michael Burry said the filing changes nothing about his AI bear case, pointing to financial risks beyond the technology. (Anthropic makes Claude, so I'm reporting what's published rather than assessing it.) Oil whipsawed, with Brent near $115 (down about 0.7%) and WTI near $101 on Iran-talks hopes after reversing early losses. Gold held near $4,000 and Bitcoin slipped below $80,000.
- Asia rallied on the Nasdaq-led lead. South Korea's KOSPI rose 3.1% to 5,638.34 after jumping more than 4% intraday, which triggered a sidecar halt on program trading; SK Hynix gained about 7% and Samsung 4.8% at the high. Korea's Q3 GDP grew 1.0% on the quarter, beating forecasts as AI-chip exports surged. Japan's Nikkei 225 gained 1.73% to 63,268.37, with Advantest up 9.6% and SoftBank up 5%, while the Topix rose 0.61% to 3,997.37.
- China and Hong Kong lagged. The Hang Seng fell 0.73% to 23,041.32 after HSBC missed revenue estimates, and the Shanghai Composite dropped 1.33% to 3,648.30 as traders awaited news from a closed-door Communist Party plenum. That came despite September industrial profits jumping 14.4% year over year, rebounding from 4.2% in August. Taiwan's Taiex rose about 0.1%, India's Sensex slipped 0.5%, and Australia's ASX 200 gained about 0.5% to near 8,850 ahead of key inflation data. The yen weakened to about 157.8 per dollar.
Global Indices:
 Sage Kakkat
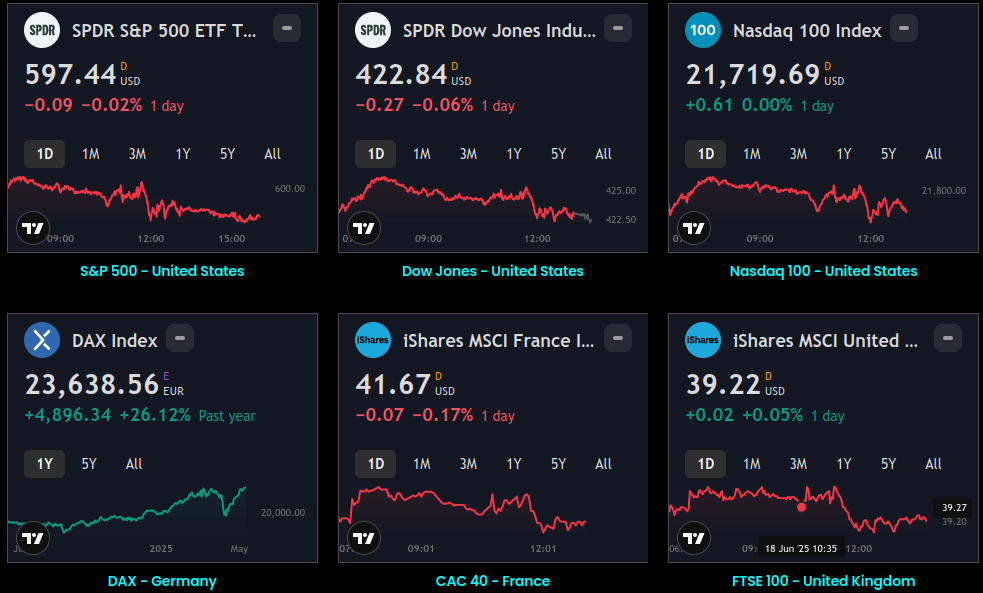
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
