US Stocks closed mixed as a record one-day drop in Alphabet dragged the Nasdaq down 1.4% even though most stocks rose: Alphabet missed on revenue and earnings, slowed in advertising and burned cash, reviving worries about whether AI spending will pay off. Q3 GDP came in stronger than expected at 3.4%, but September's PCE inflation ran hotter at 3.6% (core 3.1%), keeping a December Fed hike in play after Wednesday's 10–2 hold with two hawkish dissents. The Russell 2000 gained 1%, Microsoft rose on a strong Azure quarter, and Samsung fell despite a record profit. Amazon reports after the bell.
- The S&P 500 fell 23.59 points (0.3%) to 7,720.39, its first drop in four sessions, the Nasdaq Composite lost 365.13 (1.4%) to 26,184.72 and the Dow dropped 132.54 (0.3%) to 52,342.56. The Russell 2000 rose 28.71 points (1.0%) to 2,859.22, and Treasury yields fell. For the week, the S&P is up 1.3%, the Nasdaq 0.9%, the Dow 0.2% and the Russell 2000 3.0%. Semiconductors fell about 2% and software was weak after results from Fortinet (down roughly 20%) and ServiceNow, while Caterpillar dropped sharply on its results.
- Alphabet (GOOGL) had its worst drop on record, falling roughly 13%, after Q3 adjusted EPS of $2.12 and revenue missed estimates and advertising growth slowed. Cloud revenue grew about 103% and quarterly capex hit $51.4 billion, but the company's accelerating AI-related cash burn and negative free cash flow overshadowed the cloud boom. That put Alphabet at the center of the market's question: with capex of $195–205 billion guided for 2026, when does the spending produce returns?
- Microsoft (MSFT) gained about 3% after fiscal first-quarter revenue rose 19% to $92.3 billion, Azure grew 48%, Microsoft Cloud revenue rose 30% to $63.9 billion and commercial remaining performance obligations jumped 73% to $677 billion. Capex and finance leases were $45.2 billion, below the roughly $50 billion guided, which CFO Amy Hood attributed to delayed third-party capacity deliveries. Of the 253 S&P 500 companies that had reported, 81% beat expectations, with analysts expecting aggregate earnings growth of 31% year over year. Amazon reports after the close, with Intel and Sandisk also on deck to confirm chip and memory demand.
- Data was mixed. The first estimate of Q3 GDP showed 3.4% growth against a 3.1% consensus (after 2.2% in Q2). The September PCE price index rose 0.5% on the month and 3.6% from a year earlier (up from 3.4%), with core PCE rising to 3.1% from 3.0%, which reinforced bets on a December hike after Wednesday's hold at 3.75–4.00%. Gold, Brent and Bitcoin slipped in the morning session.
- Asia was mixed on Alphabet's after-hours plunge and Samsung's report. Japan's Nikkei 225 rose 1.0% to 64,595, with chip-test maker Advantest up 5.9% and Furukawa Electric up 5.3%, and the Topix gained about 0.3% on the day of its largest-ever index rebalancing, which was expected to trigger around $60 billion of passive trading at the close. Australia's S&P/ASX 200 rose 0.5% to about 8,892, Singapore's STI gained 0.2% and India's Nifty 50 rose 0.6%.
- South Korea's KOSPI fell 1.2% after dropping as much as 3% intraday, as Samsung Electronics slid nearly 4–5% despite reporting the first-ever quarterly operating profit above 100 trillion won and a more-than-500% jump in net income. Investors focused on a miss in chip profit expectations and uncertainty over shareholder returns, a reminder that the bar is high after SK Hynix's blowout. Mainland China and Hong Kong fell as chip stocks led losses: the Shanghai Composite dropped 0.8%, the CSI 300 slipped 1.0% and the Hang Seng lost 0.5%, with the Hang Seng Tech sub-index down 2.6%, even as the PBoC kept up open-market liquidity operations of more than 1 trillion yuan. The Bank of Japan concludes its two-day meeting Friday, with a hold at 1.25% expected, and USD/JPY sits near 157.8.
Global Indices:
 Sage Kakkat
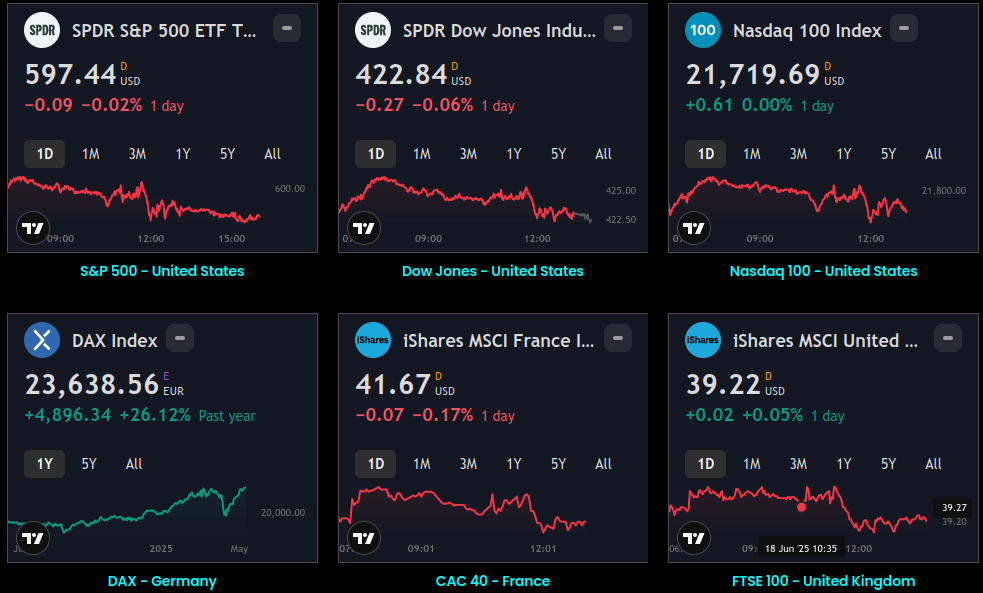
Active Stocks:
 Sage Kakkat
Stocks, ETFs and Funds Screener:
 Sage Kakkat
Forex:
 Sage Kakkat
CryptoCurrency:
 Sage Kakkat
Events and Earnings Calendar:
 Sage Kakkat
This daily briefing is curated from a wide range of reputable sources including news wires, research desks, and financial data providers. The insights presented here are a synthesis of key developments across global markets, intended to inform and spark thought.
No Investment Advice: This content is for informational purposes only and does not constitute investment advice, recommendation, or endorsement.
Timing Note: Each edition is assembled based on the market context available at the time of writing. Timing, emphasis, and interpretations may vary depending on global developments and publishing windows.
